
Start with what matters to you
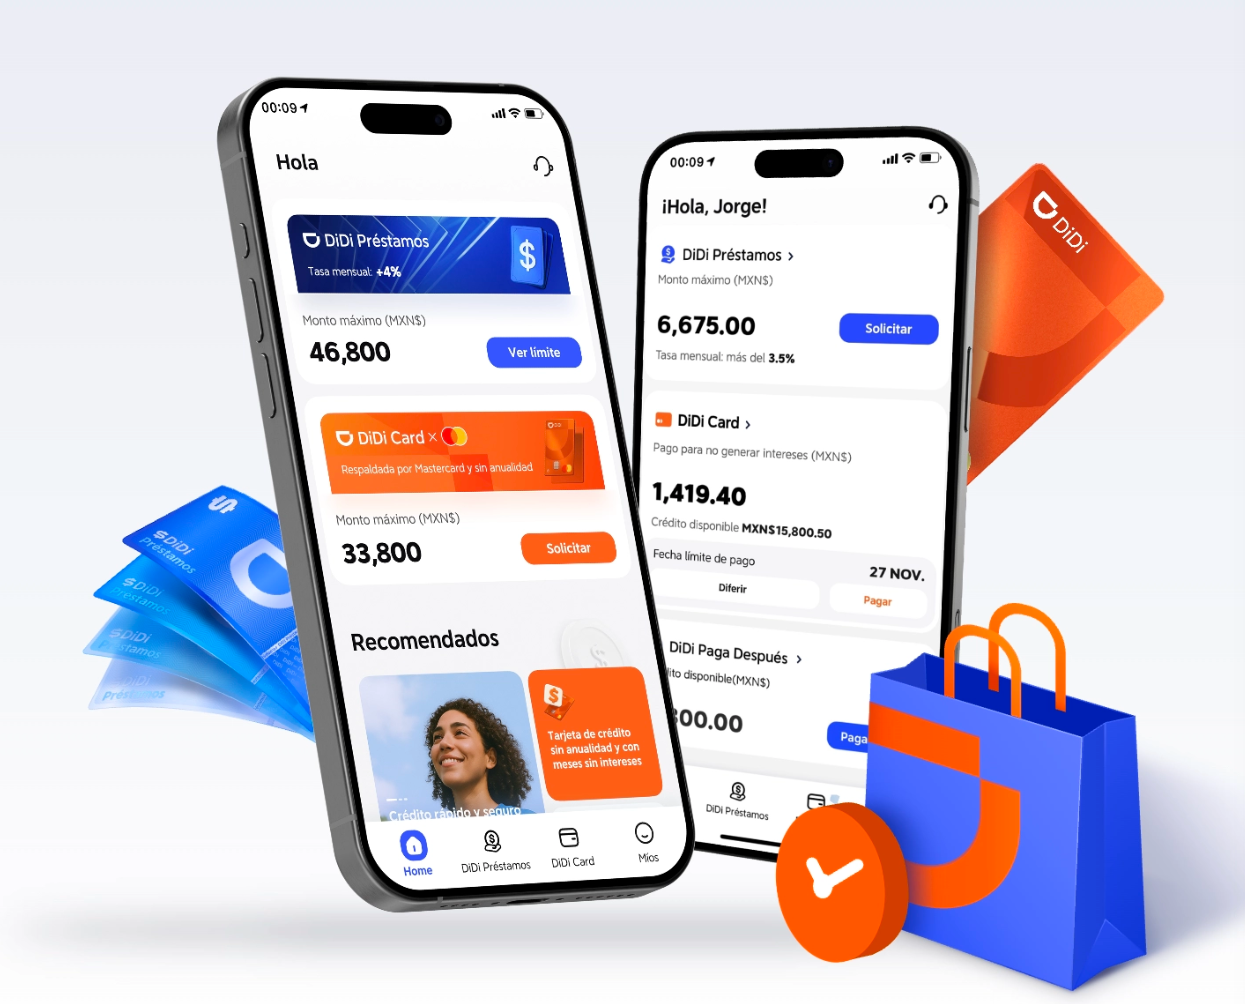
Inflation pinches wallets in Mexico, and the person who feels it most is the everyday buyer juggling groceries, transport, and family bills. This piece is written for that person — you — who wants straightforward steps to protect spending power using fintech tools. Begin by checking the basics: your monthly cash flow, any existing debt, and short-term goals. For practical help that ties these pieces together, consider platforms like didi finanzas which aim to make small loans and payments clearer for users.
Why a user-first approach beats jargon
Finance apps push features, but you need outcomes. A user-centric approach flips the view: match tools to a real need (emergency fund, bill smoothing, or a small investment). Real-world anchors matter here — Mexico’s INEGI publishes CPI figures that show price shifts month-to-month, so decisions should be tied to living costs, not flashy product pages. Keep it simple: track actual spending for two weeks, then decide if an online loan or a digital wallet will help stabilise cash flow without increasing financial stress.
Practical saving moves using online loan apps
Start with three actions you can do this week. First, set a micro-budget for essentials only. Second, use a loan app sparingly to smooth timing gaps — pick short-term loans with transparent interest rates and APR. Third, automate a tiny transfer to a savings bucket the day payday lands. Small wins add up.
How to pick an app and avoid common pitfalls
Not all apps are built equal. Look for clear loan origination notes, easy-to-read repayment schedules, and a support channel that answers fast. Avoid apps that hide fees in fine print or lock you into complex rollover cycles — those are traps that eat savings. A quick red flag list: opaque fees, lengthy processing delays, and aggressive push to take larger loans than you need. — Be picky; it saves you trouble later.
Comparing DiDi Finanzas and alternatives
DiDi Finanzas sits among several microloan and fintech players. Compared to informal credit or payday lenders, regulated platforms often show interest rate tables and user agreements up front. Alternatives include credit unions, bank overdrafts with known fees, and peer-to-peer options. Each has trade-offs: banks may be cheaper but slower; P2P can be competitive but variable. Weigh speed against cost, and pick the solution that matches urgency to affordability.
Common mistakes people make — and how to dodge them
Most slip-ups come from ignoring the fine print, underestimating interest, or using loans to fund ongoing shortfalls instead of one-off gaps. Keep records of every transaction, and reconcile monthly. If you spot repeated shortfalls, it’s time to cut expenses or renegotiate bigger bills — not borrow more. Also, confirm whether a provider is transparent about credit reporting and how repayments affect your credit score — that matters for future access to cheaper credit. — Little checks now avoid big headaches later.
Summing up the smart playbook
Save with intent: prioritise predictable expenses, use short-term lending only for timing issues, and pick platforms that show interest rates and repayment terms plainly. Cross-reference choices with recognized data sources like INEGI to see if prices are shifting in ways that warrant a different plan. Trust builds from transparency — which is why many users ask whether didi finanzas es confiable when evaluating options.
Three golden rules for choosing tools and strategies
1) Cost clarity: Always confirm the total cost (APR or equivalent) before clicking accept. 2) Match horizon: Use short-term loans only for short gaps; plan longer-term solutions for chronic budget strains. 3) Service reliability: Pick platforms with clear customer support and visible repayment records — these reduce surprises.
Make those rules your checklist, and you’ll make smarter choices about when to borrow and when to save. DiDi Finanzas fits naturally into this playbook as one of the practical tools that can help you keep peso power — a simple, steady aid rather than a headline-grabbing shortcut. –